












By Abiodun Folarin
WorldStage— The National Insurance Commission (NAICOM), has warned insurance companies that successful completion of the recapitalisation exercise does not guarantee financial stability, urging boards of directors to strengthen corporate governance, risk management and capital deployment to ensure long term institutional resilience.
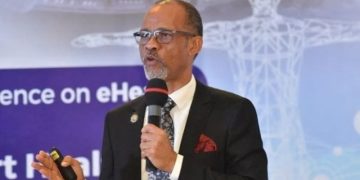
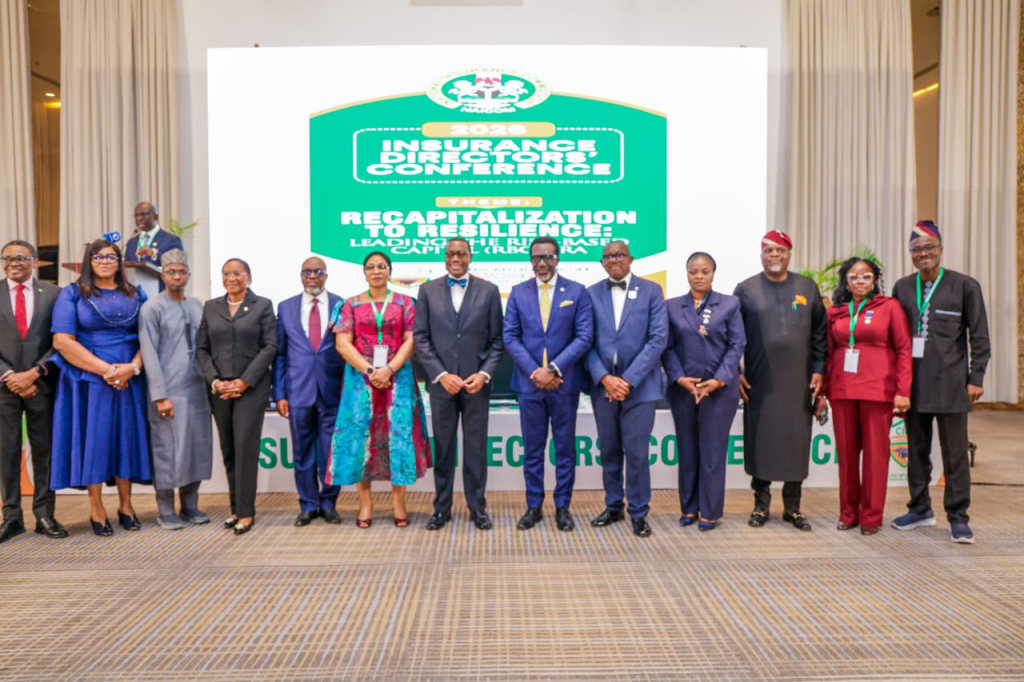
The Commissioner for Insurance and Chief Executive of NAICOM, Olusegun Omosehin, said this on Thursday at the 8th Annual Insurance Directors’ Conference theme: ‘Recapitalisation to Resilience: Leading the Risk-Based Capital Era’, in Lagos.
He said the industry must move beyond meeting minimum capital requirements to demonstrating the capacity to withstand financial shocks, manage emerging risks and meet obligations to policyholders.
Omosehin, said the transition to the Risk Based Capital (RBC) regime would place greater responsibility on insurance company boards to ensure that strengthened capital positions translate into improved underwriting capacity, operational efficiency and sustainable growth.
He described recapitalisation as a foundation rather than the ultimate objective of industry reform, stressing that the real test would be how effectively companies govern, protect and deploy their capital in line with their risk exposures.
“Recapitalisation was never the destination; it is the gateway to a more demanding phase, a phase that will be defined not by the size of capital alone, but by how that capital is governed, protected, deployed and aligned with risk,” he said.
According to him, a well capitalised insurance institution is not necessarily a resilient one, as financial institutions can still fail despite substantial capital due to poor governance, weak internal controls, ineffective risk management, inappropriate investments and inadequate board oversight.
He identified climate related disasters, cyber threats, technological disruptions, economic volatility and geopolitical uncertainties as emerging challenges requiring insurance companies to adopt more responsive and risk sensitive business models.
The commissioner said changing customer expectations, including demands for transparency, faster claims settlement, personalised products and improved digital services, also required insurers to strengthen their operational capacity and public confidence.
Omosehin emphasised that corporate governance would be central to the success of the post-recapitalisation era, calling on directors to take greater responsibility for strategic leadership, capital stewardship, risk governance and management accountability.
He urged boards to move away from merely receiving management reports to actively interrogating business strategies, challenging management assumptions and ensuring that institutional decisions are supported by adequate information and sound judgment.
He also cautioned against allowing shareholder expectations for higher returns and business expansion to undermine prudential considerations, board independence and sustainable business strategies.
“Shareholder interests must not override prudential considerations, undermine board independence or encourage management to pursue unsustainable business strategies,” he said.
On the new regulatory framework, the NAICOM chief explained that while the Minimum Capital Requirement (MCR) establishes the minimum capital threshold for an insurance institution to undertake its licensed business, Risk-Based Capital assesses the risks assumed by an institution and the capital required to support those exposures.
He noted that an insurance company could meet its minimum capital requirement and still have insufficient capital relative to the nature, scale and complexity of its risks.
Omosehin said NAICOM would increasingly focus its supervisory activities on capital quality, risk management frameworks, governance effectiveness, institutional resilience and companies’ capacity to meet policyholder obligations.
He added that the commission would place greater emphasis on the accuracy and reliability of regulatory returns, financial reporting, actuarial assessments and disclosures, warning that successful recapitalisation would not grant insurance companies permanent immunity from regulatory scrutiny.
“Capital adequacy is a continuous responsibility. Institutions must remain financially sound and compliant throughout their operations,” he stated.
The commissioner further called on insurance boards to ensure that internal audit, compliance, risk management and actuarial functions were adequately resourced, independent and empowered to report institutional weaknesses without interference.
He also stressed the importance of the Fit and Proper Framework, saying appointments to boards and senior management positions must be based on competence, character, experience and professional integrity rather than status, influence or personal relationships.
Beyond strengthening individual companies, Omosehin said recapitalisation had significant implications for Nigeria’s economic development, particularly in infrastructure, energy, manufacturing, agriculture and construction, where stronger insurance capacity was needed to support investments and manage complex risks.
He said a financially stronger insurance industry could deepen domestic risk-retention capacity, reduce dependence on foreign insurance markets, support long-term investment and expand access to affordable insurance products.
However, he challenged insurance companies to translate their strengthened capital positions into greater economic relevance through innovative products, improved service delivery, wider insurance penetration and prompt settlement of genuine claims.
The commissioner maintained that policyholder protection must remain at the centre of corporate strategies, noting that public confidence in insurance companies would ultimately depend on their willingness and ability to honour contractual obligations when claims arise.
He urged directors to recognise their expanded responsibilities in the post-recapitalisation era, describing them as custodians of policyholders’ trust, shareholders’ investments and institutional integrity.
Omosehin said the decisions taken by insurance boards would determine whether the gains of recapitalisation would be sustained and whether the industry could become more competitive and relevant to Nigeria’s economic development.