


















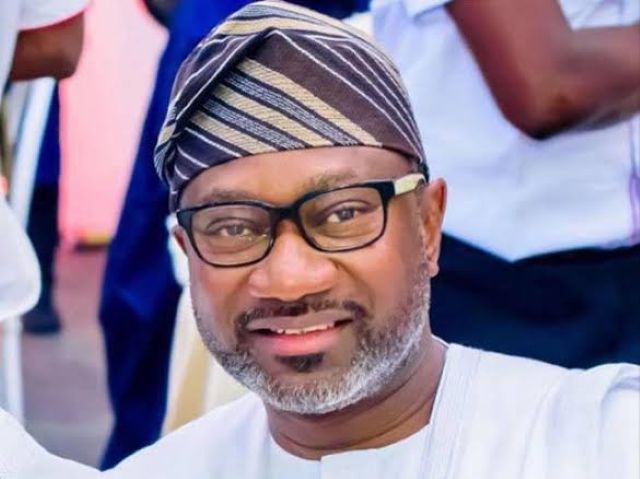
WorldStage– As Femi Otedola, Nigerian billionaire and Group Chairman of First HoldCo Plc, the parent of First Bank of Nigeria, pursues an aggressive, multi-year share accumulation strategy that has made him the largest individual/beneficial shareholder, WorldStage can now forecast that he is within the reach of 30% ownership to trigger mandatory takeover of of the financial group in matter of weeks with realistic path to 51% controlling stake put at 2027.
From the low-to-mid teens percent range in 2024–mid-2025, Otedola’s combined direct and indirect holdings via vehicles including Calvados Global Services Limited rose to 18% by end-2025, 20.4% by mid-2026, and approximately 27.5% (around 12.05 billion shares) by mid-August 2026 after a series of large open-market and private-placement purchases.
He further solidified his dominant position in the financial services giant after acquiring an additional 95,699,240 ordinary shares according to a regulatory filing submitted to the Nigerian Exchange Limited (NGX) on August 24, 2026, the transaction was executed at ₦131.48 per share, bringing the total value of the fresh capital injection to ₦12.58 billion.
The newly acquired block represents roughly 0.21% of the company’s total outstanding equity.
Related stories
Femi Otedola expands First HoldCo stake to 27.7% in N12.58b acquisition, closer to the 30% threshold
Femi Otedola raises overall stake in First HoldCo to 27.5% with fresh ₦20.7b share purchase
Otedola’s interest in First HoldCo jumps to 26% as Calvados Global Services buys fresh 138m shares
Femi Otedola succeeds Ahmad Abdullahi as Chairman of FBN Holdings
FBN Holdings appoints Otedola associate as Non-Executive Director
FBN Holdings confirms Otedola’s acquisition of 5.07% equity stake
FBN Holdings denies any notification of Otedola’s acquisition
Femi Otedola dumps Forte Oil, sells 75% stake
Mixed reactions trail Otedola’s move to buyout Forte Oil upstream, power firm
Prudent Energy confirmed to pick Otedola’s 75% equity in Forte Oil
Following this transaction, Otedola’s total direct and indirect shareholding rises to approximately 12.14 billion shares, elevating his overall ownership stake to 27.70%.
Otedola has spent roughly over ₦650 billion in the acquisitions. Major disclosed purchases in 2026 alone have exceeded ₦400 billion in aggregate according to tracking reports. He is now holding approximately 12.14–12.15 billion shares (27.7% ownership estimated at ₦1.56–1.58 trillion
Going by this trend, his interest framed as a long-term, generational commitment rather than a short-term trade or flip, the billionaire may cross the 30% ownership threshold which would trigger a mandatory takeover offer under Nigerian rules before the end of 2026 based on WorldStage projection.
With about 27.7% share already in the kitty, Otedola will now need authorisation from the Security and Exchange Commission (SEC) before completing the remaining 2.3% acquisition that would push him to over 30%. Previous transactions showed that he can pick the remaining 2.3% needed shares in one transaction.
In late July 2026, the billionaire through Calvados Global Services Limited acquired 1,779,094,976 ordinary shares of First HoldCo Plc in a single disclosed transaction. This block represented approximately 3.91% of the company’s then-outstanding shares (on a register of roughly 45.475–45.48 billion shares) and cost about ₦222.2 billion. It was his largest single reported purchase and well above a 2.5% stake.
At the current accelerated rate of accumulation, Otedola is on a trajectory that could see him cross the 51% controlling stake threshold sometime in 2027.
WHAT THE LAW SAYS
Crossing 30% triggers a mandatory takeover offer (also called a mandatory bid or mandatory tender offer) under Nigerian capital market rules.
The primary legal basis is the Investments and Securities Act (ISA) 2025 (which repealed and replaced the older Investments and Securities Act 2007).
Section 142 of the ISA 2025 says a person shall not acquire shares (whether by a single transaction or a series of transactions) that carry 30% or more of the voting rights of a company; the same restriction applies if the person is acting in concert with others, and their combined holdings reach or exceed 30%; anyone intending to acquire 30% or more must make a takeover bid (offer) to the other shareholders of the company.
This is reinforced by the Securities and Exchange Commission (SEC) Rules made under the ISA, which govern the detailed procedure for takeover bids, disclosures, pricing, and timelines.
What the Mandatory Offer Requires
When the 30% threshold is crossed (or is about to be crossed): the acquirer must make a formal takeover bid offering to buy the shares of all remaining shareholders, the offer price is typically required to be at least as high as the highest price the acquirer (or concert parties) paid for shares in a recent look-back period (often the preceding 12 months); the process is supervised by the Securities and Exchange Commission (SEC) to ensure fairness, transparency, and equal treatment of minority shareholders; the acquirer generally needs prior authorisation from the SEC before completing the acquisition that would push them over 30%.
PROJECTION
While there is no official or published analyst forecast with specific dates for when Femi Otedola will reach 30% or 51% ownership of First HoldCo, WorldStage can report that if buying continues at a sustained pace similar to the post-July acceleration, the 30% threshold could potentially be reached in weeks to a few months, assuming sufficient liquidity and no major interruptions.
As of the latest disclosed transaction on 24 August 2026, Otedola stake stands at 27.70%, approximately 12.14 billion shares out of the 45.48 billion total issued/outstanding shares of the company.
He will now need to buy 1.0–1.05 billion shares to fill the 2.3% points gap on the path to 30%. At recent prices of around ₦130, this would require on the order of ₦1.3–1.4 trillion or more (higher if the share price continues rising).
Path to 51%
A realistic path to 51%, if pursued, would more likely span well into 2027, potentially involving a mix of open-market purchases, negotiated blocks, participation in any future capital raises, or other structures—subject to approvals.
Otedola has framed this as a long-term, generational commitment rather than a short-term trade.
Key Assumptions & Risks
- No major new capital raises or rights issues that significantly increase total shares outstanding (further dilution would push the timeline later).
- Sufficient liquidity and willing sellers continue to exist in the market.
- Otedola continues deploying capital at a similar rate (he has already stated a clear preference for >51% control).
- Crossing 30% would trigger a mandatory takeover offer under Nigerian rules, which could accelerate or alter his strategy.
- Share price rises (currently ~₦130) would make further large purchases more expensive, potentially slowing the pace.
CHRONOLOGICAL LIST OF OTEDOLA’S ACQUISITIONS OF SHARES IN FIRST HOLDCO
Early Phase (2021 – Building Initial Stake)
Around July–October 2021: Began accumulating shares. By 23 October 2021, Otedola (personally and via Calvados Global Services) held a total of 1,818,551,625 shares (5.07% of issued capital). This made him a substantial shareholder.
By 9 December 2021: Additional purchases (via proxies including Calvados, Primose Global Concept, Shetland Global, Wells Properties, and Impetus Synergy) raised his total holding to approximately 2.717 billion shares (7.57%). Reported investment at this stage ₦44.8 billion.
Intermediate Build-up (2022–2024): Steady accumulation continued. By end-2023 (just before he became Chairman in January 2024), holdings stood at roughly 2.03 billion shares (5.65%)
By end-2024: Holdings more than doubled to approximately 4.23 billion shares (11.8%).
September 2024: Acquired 534.09 million shares at ₦30.00 each ( ₦16 billion). This helped push the stake above 13%.
Accelerated Accumulation (2025–2026)
23 September 2025:Direct: 39,313,379 shares at ₦31.Via Calvados: 25,565,289 shares at ₦31.
Total: 64.88 million shares (≈ ₦2.01 billion). Stake rose to 16.1%.
18 December 2025: Via Calvados – 369,986,122 shares at ₦40.06 ( ₦14.82 billion). Combined stake reached 18.12% by year-end 2025 (total holding ≈8.055 billion shares).
13 May 2026: Via Calvados – 549,535,653 shares at average ₦79 (₦43.41 billion). Holding rose to 8.605 billion shares (19.36%).
June 2026 (private placement, second tranche of N350 billion programme): 672.9–680.8 million new shares at ₦44 (₦29.6–30 billion). Total holding 9.286 billion shares (20.4–20.42%).
22 July 2026: Via Calvados – 706,131,179 shares at ₦109.88 ( ₦77.58–77.59 billion). Holding rose to 9.984 billion shares (21.95–21.96%).
Late July 2026 (around 30–31 July): Via Calvados – 1,779,094,976 shares at ₦124.90 (₦222.21 billion). Holding rose to 11.763 billion shares (25.87–26%).
6 August 2026: Via Calvados – 138,041,465 shares at ₦131.20 ( ₦18.11 billion). Holding 11.99 billion shares (26.1%).
14 August 2026: Via Calvados – 147.74 million shares at ₦140 ( ₦20.68–20.7 billion). Holding rose further (reports indicate 12.13–12+ billion shares / 26.4–27.49% depending on exact issued capital at the time).
August 24, 2026: Additional 95,699,240 ordinary shares through Calvados Global Services Limited executed at ₦131.48 per share, bringing the total value of the fresh capital injection to ₦12.58 billion and overall ownership stake to 27.70%.
WAR ROOM STRATEGY
Otedola’s accumulation of a major stake in First HoldCo through Calvados Global Services Limited can reasonably be compared to a corporate “war room” campaign.
1. Clear Strategic Objective
- War room: Defined end-state (e.g., capture a key position, achieve dominance, or force a surrender/settlement).
- Otedola: Explicit long-term goal of building ownership “over and above 51%” for firm control to drive reforms, while still respecting minority interests. He has framed it as a generational commitment rather than a short-term trade. The 30% mandatory-offer threshold acts as an intermediate “objective.”
2. Use of a Specialised Vehicle
- War room: Often deploys specialised units, proxies, or shell entities to execute moves while protecting the main force or maintaining operational flexibility.
- Otedola: Calvados Global Services Limited functions as the primary acquisition vehicle for many of the large disclosed purchases. It allows concentrated buying under a related-party structure, keeps the transactions cleanly reportable as insider dealings, and separates the buying activity from his personal name in day-to-day market impact.
3. Phased, Coordinated Campaign
- War room: Sequential advances, probing attacks, then larger pushes once conditions are favourable; continuous reassessment of terrain and enemy strength.
- Otedola: Multi-year build-up that accelerated sharply in 2026. Earlier modest holdings grew steadily; then came rapid large-block purchases (hundreds of millions to nearly 1.8 billion shares in single transactions) timed around strong earnings, rising share prices, and improving market sentiment. The pattern shows measured escalation rather than one-shot aggression.
4. Resource Concentration and Intensity
- War room: Massive, focused deployment of capital, intelligence, and attention on a single front.
- Otedola: Hundreds of billions of naira of personal wealth committed (over ₦600 billion stated, with further August purchases pushing the total higher). Attention is highly concentrated on one institution while he already holds the chairmanship — giving him both economic and governance leverage.
5. Information and Signalling Advantage
- War room: Real-time intelligence, controlled messaging, and psychological operations.
- Otedola: As Chairman he has superior visibility into the company’s trajectory. Public interviews signal long-term intent (softening market and regulatory reaction), while the actual buying is executed through formal regulatory disclosures. The combination of transparent intent + aggressive execution creates both credibility and pressure.
6. Regulatory and Market “Battlefield”
- War room: Navigating rules of engagement, terrain constraints, and potential counter-moves.
- Otedola: Must manage Nigerian securities rules (especially the 30% mandatory takeover trigger), CBN oversight of significant bank ownership, free-float requirements, and market liquidity. Using Calvados and spaced transactions helps manage optics and compliance while still advancing the position.
Key Differences from a Classic Hostile War Room
- This is not a classic hostile takeover. Otedola already chairs the board and presents the campaign as value-creating and aligned with the company’s turnaround.
- There is significant transparency via NGX filings rather than pure stealth.
- The “enemy” is not a defending management team but rather market liquidity, price levels, regulatory thresholds, and the sheer capital required to reach majority control.
The Calvados-driven accumulation has the hallmarks of a disciplined war-room operation — clear objective, specialised vehicle, phased escalation, concentrated resources, and careful navigation of the regulatory terrain — executed in the more transparent and regulated environment of a listed Nigerian financial holding company. It is less “surprise assault” and more “sustained campaign of controlled advances toward majority control.”
ABOUT CALVADOS GLOBAL SERVICES LIMITED
Calvados Global Services Limited, a Nigerian private limited company is not a widely known public-facing operating company. It is primarily an investment holding and acquisition vehicle controlled by/related to Femi Otedola, used both for his power-sector interests (via Amperion/Geregu) and for building his substantial stake in First HoldCo.
It was incorporated on 7 March 2017 under the Corporate Affairs Commission (RC-1395852). It is a private company limited by shares.
According to its official description, the company is authorised to operate across several sectors, including: Investment in stocks, bonds and securities, Real estate, Manufacturing, General merchant activities, Oil and gas, Other related businesses
Regulatory filings with the Nigerian Exchange (NGX) consistently describe Calvados as “a company related to a significant shareholder – Mr. Olufemi Otedola.”; Otedola is listed as Chairman on the company’s website; Family members (including his daughters) appear as directors.
It functions as his primary vehicle for large share purchases in First HoldCo Plc. Most of the major block trades that raised his stake (from low-teens percentages to the current 27.7%) have been executed through Calvados rather than in his personal name.
Calvados has been the buyer in the majority of the large disclosed insider transactions in 2025–2026. These purchases are reported as insider dealings because of Otedola’s position as Chairman and significant shareholder of First HoldCo.
Using the company allows concentrated, structured accumulation while remaining fully compliant with disclosure rules.
PUBLIC PERCEPTION OF FIRST HOLDCO ACQUISITION
Public perception of Femi Otedola’s plan to acquire a majority (>51%) stake in First HoldCo is generally positive-to-cautiously supportive, based on media coverage, analyst comments, and recent online discussion (as of mid-to-late August 2026).
Positive Views (Dominant Tone)
- Market confidence booster: Many analysts and market participants credit Otedola’s aggressive buying and stated long-term commitment with helping drive First HoldCo’s strong share-price rally (the stock has more than tripled in value in 2026 in some periods). His continued personal capital injection is widely seen as a strong vote of confidence in the bank’s turnaround.
- Track record matters: Commentators frequently reference his successful previous transformations (Forte Oil / African Petroleum and Geregu Power), where he also built controlling stakes and delivered value. His statement that “firm shareholder control with due regard for minority interest” is needed for deep reforms is often accepted at face value.
- Shareholder value: Analysts such as David Adonri (Highcap Securities) and others have noted that minority shareholders have benefited from the price appreciation tied to his accumulation. The market response so far has been described as positive.
- Stability after past turmoil: After years of governance disputes and shareholder battles at First Bank / First HoldCo, many view a committed, well-capitalised anchor investor as preferable to fragmented ownership.
Cautious or Neutral Notes
- Cost and feasibility: Some coverage highlights that reaching 51% would be extremely expensive (potentially requiring another ₦1+ trillion at current prices) and could take time, especially with the 30% mandatory takeover-offer threshold under the Investments and Securities Act 2025.
- Regulatory scrutiny: There is awareness that crossing 30% will trigger a formal mandatory bid process supervised by the SEC, and any move toward majority control of a systemically important bank will also face Central Bank of Nigeria oversight.
- Concentration of power: A minority of voices note the risk of excessive influence by one individual in Nigeria’s oldest and one of its largest banks, though this has not become a major public controversy.
- Who is selling?: Occasional questions appear about the source of the large blocks he is buying (especially given the size of recent transactions).
Overall public and market perception leans supportive or at least accepting. Otedola’s plan is framed more as a credible long-term commitment to rebuilding a major Nigerian institution than as a hostile or opportunistic takeover. The rising share price and improved financial performance of First HoldCo have reinforced the positive narrative so far. Significant pushback would likely only emerge if the mandatory offer process (at 30%) or the path to 51% raises clear fairness or regulatory concerns.
FIRST HOLDCO STAFF PERCEPTION OF ACQUISITION
No recent union statements, staff surveys, or widespread anonymous employee comments specifically addressing the Otedola’s 51% ambition have appeared in major outlets as of late August 2026.
What is known or can be inferred include;
- Otedola’s own framing: In his August 2026 interview, he has spoken about past cultural problems at the bank (pre-2021 emphasis on related-party interests over risk management and “very little emphasis on workforce motivation”). He positions his deeper involvement and long-term capital commitment as part of building a stronger institution that will ultimately benefit employees through sustained growth, better processes, and a healthier culture.
- Past staff-related developments under his chairmanship (context for current mood):
- There were significant senior staff exits/restructuring in 2024–2025 (reports of 100 senior staff affected in some rounds), which created anxiety at the time.
- Earlier complaints (from union-linked or LinkedIn-type discussions) have occasionally surfaced about contract/outsourced staff conditions, stagnant promotions, and benefits.
- These issues pre-date or overlap with his growing influence and are not uniquely tied to the latest 51% comments.
- No strong public opposition from staff: Unlike earlier shareholder disputes (2024–early 2025), there are no visible organised staff protests, union statements from ASSBIFI (the senior staff union for banks), or leaked internal memos reacting negatively to the majority-control plan. The absence of such reports suggests the issue has not become a major internal flashpoint so far — or that staff views remain private.
Publicly visible staff perception is essentially muted or unreported. Employees appear more focused on day-to-day operational recovery, recapitalisation outcomes, and job security than on publicly debating the ownership structure.
Any internal views (positive hope for stability and investment versus concern about further restructuring or concentrated control) are not being aired openly.
If new developments emerge (e.g., union statements, anonymous staff interviews, or internal communications becoming public), the picture could change. At present, however, there is no clear evidence of widespread staff enthusiasm or organised resistance specifically to the 51% plan.
ABOUT FEMI OTEDOLA
Femi Otedola (full name: Olufemi Peter Otedola, CON) is a prominent Nigerian businessman, investor, and philanthropist.
Personal Background
- Born: 4 November 1962 in Ibadan, Oyo State, Nigeria (age 63 as of 2026).
- Ethnicity: Yoruba; family roots in Epe, Lagos State.
- Father: Late Sir Michael Otedola, who served as Governor of Lagos State (1992–1993).
- Education: Methodist Boys’ High School, Lagos, and Olivet Baptist High School.
- Family: Married to Nana Otedola. They have four children, including Florence Ifeoluwa Otedola (popularly known as DJ Cuppy) and actress/model Temi Otedola.
- National Honour: Commander of the Order of the Niger (CON), conferred in 2010.
Business Career
Otedola built his fortune through successive turnarounds and strategic investments:
- Early career: Started in commodities trading.
- Zenon Petroleum & Gas: Founded the company and disrupted Nigeria’s downstream oil sector.
- Forte Oil (formerly African Petroleum): Acquired a controlling stake in 2007, became Chairman, transformed the company, and later exited profitably.
- Geregu Power Plc: Acquired a majority stake via Amperion Power Distribution Company Limited. Grew the plant’s capacity significantly and listed it on the Nigerian Exchange. He later sold his controlling interest (around 77%) in a landmark deal valued at approximately $750 million (completed late 2025), while reportedly retaining a small residual stake.
- First HoldCo Plc (parent of First Bank of Nigeria): Became the largest individual shareholder and was appointed Chairman in January 2024. He has aggressively increased his stake (currently around 27.7% as of late August 2026) mainly through his investment vehicle Calvados Global Services Limited, with a stated long-term ambition of building ownership above 51%. He has publicly described this as a generational commitment rather than a short-term trade.
He also holds other interests in real estate, shipping, insurance, and banking (including stakes in Zenith Bank in the past).
Net Worth
As of mid-to-late August 2026, Forbes real-time estimates place his net worth at approximately $1.8 billion, up significantly during the year (from around $1.3 billion at the start of 2026). The sharp rise has been driven largely by the appreciation of his First HoldCo holding and the proceeds from the Geregu exit.
Other Roles & Philanthropy
- Former member of Nigeria’s National Economic Management Team.
- Involved in educational philanthropy through the Sir Michael Otedola Scholarship Awards Foundation.
- Author of the memoir Making It Big: Lessons from a Life in Business (published 2025).
Otedola is widely regarded as one of Nigeria’s most successful self-made (or family-influenced but independently scaled) billionaires, known for buying undervalued or troubled assets, driving operational turnarounds, and eventually exiting or consolidating control.